Professional & Financial / Real Estate, Mortgage & Property Services
Mortgage marketing built around the inquiry
Mortgage marketing from MBI is a lead program for mortgage banks, regional lenders, credit-union mortgage teams and broker platforms: a direct-mail lead campaign, Facebook lead campaigns for purchase, refinance, reverse-mortgage and home-equity inquiries, consent-based texting once an inquiry is submitted, and the printed materials the campaign calls for, produced in house.
Not sure where to start? Talk with our teamDirect mail
What is a mortgage lead generation direct mail campaign built to do?
The short answer
Mortgage lead generation direct mail is the lender's lead campaign in the mail: one program, planned, produced and delivered by a single team whose data, print and delivery have been in house since 1989. Which direct-mail piece carries it is a decision made with the lender, not an assumption made for them.
The three campaign concepts. The three researched campaign concepts for this vertical are a mortgage direct-mail lead campaign (documented in reverse-mortgage acquisition), a Facebook mortgage-inquiry lead campaign, and a consent-based post-submission SMS lead-follow-up sequence.
What the case establishes, and what it does not. A mortgage case study documents a large direct-mail lead program; the source does not establish a specific print format.
direct mail marketing services direct mail campaign measurement
Direct mail
Facebook and Instagram
Which inquiries do mortgage Facebook ads collect?
The short answer
Mortgage Facebook ads collect four kinds of inquiry: purchase, refinance, reverse-mortgage and home-equity. The campaign behind them is the Facebook mortgage-inquiry lead campaign, one of the lender's three campaign concepts. Before launch, the applicable credit, platform, privacy and licensing rules are the ones to review, and the campaign to run uses Meta's financial-products Special Ad Category.
What the sources document. Mortgage sources document Facebook lead campaigns for purchase, refinance, reverse-mortgage, and home-equity inquiries.
Meta's Advertising Standards state: 'Any United States advertiser or advertiser targeting the United States, Canada or certain parts of Europe that is running financial products and services, housing or employment ads, must self identify as a Special Ad Category, as it becomes available, and run such ads with approved targeting options.'
Meta, Advertising Standards
digital advertising services direct mail and digital marketing
Meta ad · Facebook
Reel · Instagram
SMS
When can mortgage text message marketing begin?
The short answer
Mortgage text message marketing can begin only after an inquiry is submitted, with consent, for prompt qualification and follow-up. CTIA's messaging principles say Message Senders “should support opt-in mechanisms, and messages should be sent only after the Consumer has opted-in to receive them”, and that Message Senders should ensure Consumers can opt out at any time.
CTIA Messaging Principles and Best Practices § 5.1.2: 'Message Senders should support opt-in mechanisms, and messages should be sent only after the Consumer has opted-in to receive them.' The document adds that a Consumer might demonstrate opt-in consent through several mechanisms, 'including but not limited to' six it lists, among them 'Entering a telephone number through a website'.
CTIA Messaging Principles and Best Practices, May 2023, §5.1.2
CTIA Messaging Principles and Best Practices § 5.1.3: 'Message Senders should ensure that Consumers have the ability to opt-out of receiving Messages at any time'.
CTIA Messaging Principles and Best Practices, May 2023, §5.1.3
digital advertising services direct mail and digital marketing
SMS
SMS
Printing
Which loan officer marketing materials does a readiness campaign call for?
The short answer
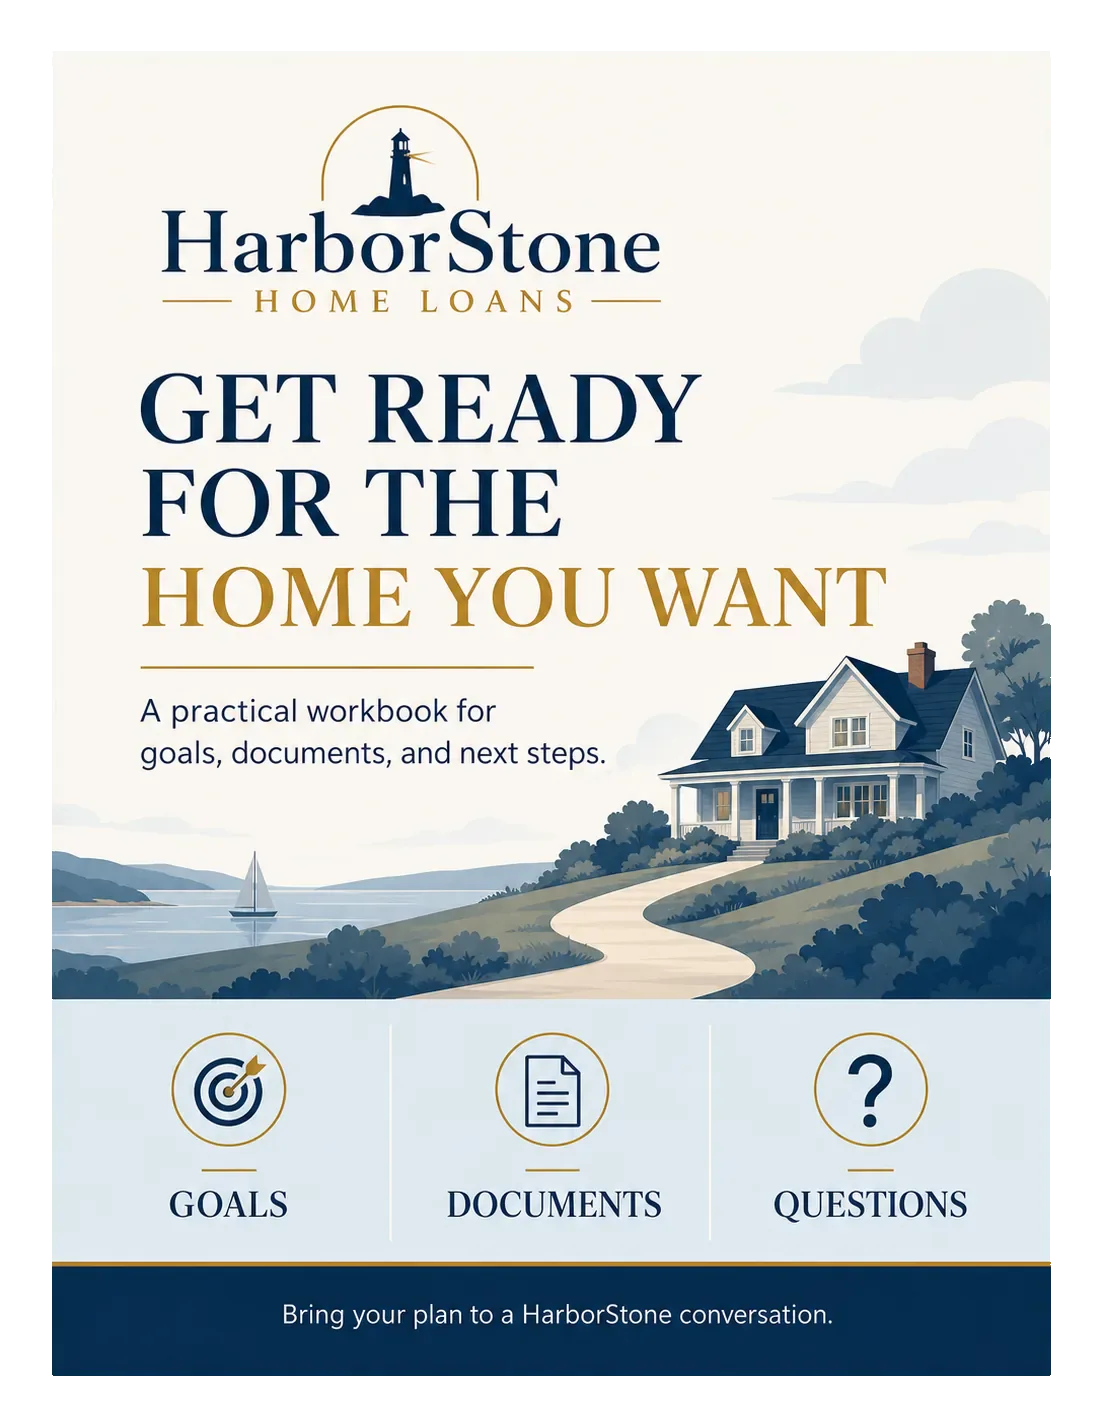
The campaign to build is homebuyer readiness — education, document checklists and consultation intake — and the loan officer marketing materials it calls for answer to the same review as the advertising: trigger terms, disclosures, licensing and fair-lending implications. MBI's printing is commercial and variable-data, in house.
In house. MBI's printing is commercial and variable-data printing, in-house.
Workbook · Printing
Checklist · Printing
Nurture
What does a lender send a preapproved or paused lead?
The short answer
For preapproved, paused and inquiry leads, the campaign to run is nurture with market and next-step content — not rate promises. For database reactivation, the campaigns to run are annual mortgage checkups and equity conversations. Neither of them carries a promise about the rate.
One-sheet · Printing
Worksheet · Printing
Regulation Z
Which terms in a mortgage advertisement trigger extra disclosures?
The short answer
Regulation Z makes four terms triggering terms in mortgage advertising: the amount or percentage of any downpayment, the number of payments or period of repayment, the amount of any payment, the amount of any finance charge. An advertisement stating one must then state, as applicable, the downpayment, the terms of repayment and the annual percentage rate, using that term.
Regulation Z § 1026.24(a): 'If an advertisement for credit states specific credit terms, it shall state only those terms that actually are or will be arranged or offered by the creditor.'
CFPB, Regulation Z, 12 CFR §1026.24(a)
Regulation Z § 1026.24(d)(1) makes four terms triggering terms in a credit advertisement: '(i) The amount or percentage of any downpayment. (ii) The number of payments or period of repayment. (iii) The amount of any payment. (iv) The amount of any finance charge.' § 1026.24(d)(2) then provides that an advertisement stating any of them 'shall state the following terms, as applicable': the amount or percentage of the downpayment; the terms of repayment, which reflect the repayment obligations over the full term of the loan, including any balloon payment; and the 'annual percentage rate,' using that term, and, if the rate may be increased after consummation, that fact.
CFPB, Regulation Z, 12 CFR §1026.24(d)
The triggering terms
Regulation Z
Questions
Questions a lender asks before it mails
Searched for mortgage marketing agency, mortgage lender marketing agency or marketing for mortgage lenders? Same work, same answers.
Which channels can a lender put behind one mortgage lead program?
Four: a direct-mail lead campaign, Facebook lead campaigns for purchase, refinance, reverse-mortgage and home-equity inquiries, consent-based texting once an inquiry is submitted, and the printed materials the campaign calls for. MBI plans, produces and delivers them from a single team in DeLand, Florida.
How is the print format for a mortgage mailing decided?
With the lender, not in advance. What a mortgage lead campaign mails is a direct-mail piece, and which one is settled with the lender before anything is produced rather than assumed by MBI, which then prints it in house.
Does Meta treat a mortgage ad differently from other ads?
Yes. Meta's Advertising Standards say: “Any United States advertiser or advertiser targeting the United States, Canada or certain parts of Europe that is running financial products and services, housing or employment ads, must self identify as a Special Ad Category, as it becomes available, and run such ads with approved targeting options”. The campaign to run uses the financial-products category.
What counts as consent to text a mortgage lead?
CTIA's messaging principles say Message Senders should support opt-in mechanisms and that messages should be sent only after the Consumer has opted-in to receive them. The mortgage campaign this governs is post-submission lead follow-up. Depending upon the circumstances, a Consumer might demonstrate opt-in consent through several mechanisms, including but not limited to entering a telephone number through a website.
Can a mortgage advertisement promise approval?
No. “Guaranteed approval” and misleading government affiliation language stay out of a mortgage campaign, and the review to run covers all trigger terms, APR, rate and payment disclosures, licensing and fair-lending implications.
Which decisions move the cost of a mortgage lead mailing?
Producing the mortgage lead mailing and mailing it are the two costs, and seven decisions move those two numbers, among them Quantity, Format and finished size, and Postage, mail class, and sortation. All seven sit on /capabilities/direct-mail/direct-mail-cost, and a lender's campaign is quoted once the audience and the piece are settled.
Which lenders does a mortgage lead program go after?
Mortgage banks, regional lenders, credit-union mortgage teams and broker platforms — the ones already carrying compliant CRM nurture and realtor or builder partner networks. That is who the campaign goes after; the program itself is the mail, the Facebook inquiry campaigns and the texting that follows an inquiry.
Get started
Start a mortgage campaign.
Say which of the campaigns it is, and what the piece has to carry. It goes to a real member of the MBI team, not a queue.